Global Gemstone & Fine Jewelry Market: Key News & Strategic Trend Outlook
The global high jewelry and precious gemstone sectors are experiencing a decisive structural transformation. As major international trade hubs close their autumn exhibition cycles and gear up for high-volume year-end showcases, market liquidity, material valuation, and consumer demand patterns are realigning around tangible rarity, geographical shifts, and modern connoisseurship.
1. Executive Market Summary & Macro News
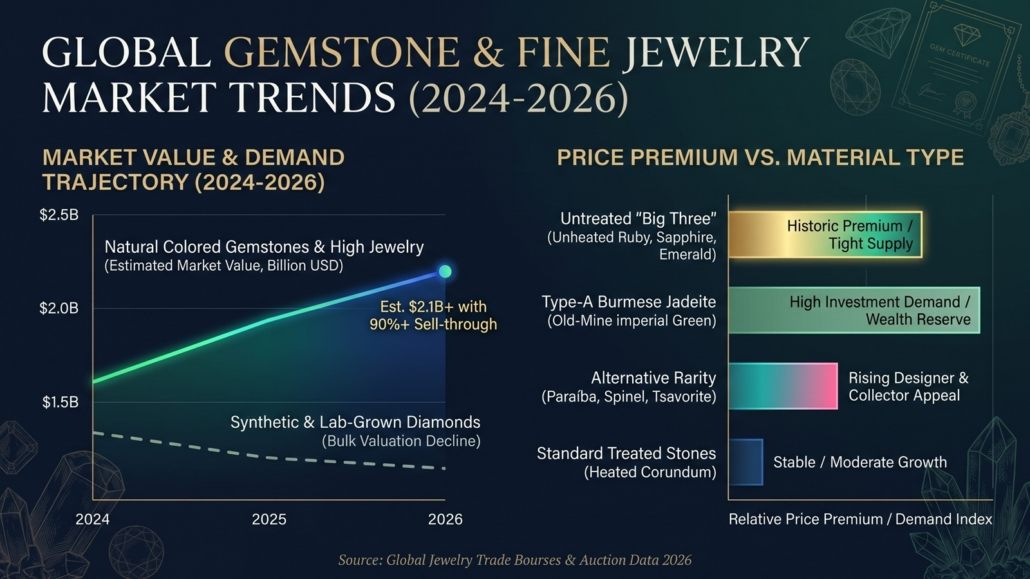
- Resilience in Natural Colored Gemstones: The global market for colored gemstones has continued its upward trajectory, on track to surpass $2.1 billion, driven by persistent luxury group allocations and institutional auctions. Auction houses and trade fairs report robust sell-through rates exceeding 90% for certified, unheated corundum and untreated emeralds.
- The Gulf Region as High Jewelry’s Commercial Epicenter: The Gulf Cooperation Council (GCC) markets—anchored by trade hubs in Dubai, Abu Dhabi, and Riyadh—have consolidated their status as prime destinations for ultra-high-net-worth individual (UHNWI) bespoke commissions. Major European heritage maisons and Asian master lapidaries are reallocating primary exhibition pieces to Middle Eastern salons to capture heightened festive and seasonal procurement.
- Lab-Grown Market Polarization: As lab-grown diamond wholesale margins compress due to expanding industrial capacity, capital is migrating toward natural, provenance-verified assets. Consumers increasingly treat lab-created stones as design-driven fashion items while viewing untreated natural colored stones and top-grade jadeite as long-term stores of value.
2. Key Material & Price Drivers
[ Natural Rarity & Origin Certification ]
                   │
                   ▼
  ┌─────────────────────────────────┐
  │   Unheated "Big Three" Stones   │ ──► Tight rough supply; auction premiums
  └─────────────────────────────────┘
  ┌─────────────────────────────────┐
  │  Untreated Grade-A Jadeite     │ ──► Asian capital flight into prime green cabochons
  └─────────────────────────────────┘
  ┌─────────────────────────────────┐
  │  Alternative Fine Colors        │ ──► Spinel, Paraíba, Spessartite, Tsavorite
  └─────────────────────────────────┘
The Unbroken Premium on Untreated “Big Three”
Sapphires, emeralds, and rubies continue to represent over 70% of high-end colored gemstone transaction value. However, the price spread between treated (heated, fracture-filled) and untreated stones has reached historic highs:
- Sapphires: Leading trade turnover (accounting for ~31% of colored gem sales). Certified unheated Ceylon (Sri Lanka) and Madagascar royal blue/cornflower material commanded double-digit auction premiums over standard heated stock.
- Emeralds: Colombian origin with negligible oil remains the gold standard, though Zambian fine crystals continue to capture significant market share among contemporary high jewelry collections.
- Rubies: High-clarity, unheated Burmese and Mozambican stones above 3 carats face severe supply bottlenecks at primary trading bourses, pushing private acquisition prices upward.
Jadeite and Imperial Green Dominance in East Asia
Across Hong Kong and mainland auction corridors, investment-grade Type-A Burmese Jadeite continues to operate in its own pricing stratosphere. Demand is heavily concentrated on old-mine (laokeng) icy and glass-variety imperial green pieces. Institutional collectors increasingly view museum-quality carved jadeite and matched bead necklaces as sovereign wealth reserves insulated from broader economic volatility.
3. Emerging Design & Consumption Trends
| Trend Dimension | Emerging Direction | Industry Impact |
| Color Combinations | Multi-chromatic suites & two-tone “Toi et Moi” rings | Moving away from monochrome sets toward expressive, complementary pairings (e.g., teal sapphire with warm yellow gold). |
| Metalwork & Settings | Sculptural bezels, brushed gold, and low profiles | High-profile claw prongs are yielding to organic, brushed, or tactile yellow gold bezels that integrate seamlessly into everyday luxury wardrobes. |
| Alternative Rarity | Spinels, Tsavorites, and Paraíba Tourmalines | Discerning buyers are aggressively pursuing clean, untreated spinels (Jeddah red, cobalt blue) and copper-bearing tourmalines as direct alternatives to standard precious stones. |
| Provenance Tracking | Blockchain ledgering and geochemical origin tracing | Gemological labs (GIA, SSEF, Gübelin) have made origin and sustainability traceability non-negotiable for retail pieces above the $50,000 threshold. |
4. Strategic Outlook for Q4 and Beyond
- Strategic Stocking for Holiday Salons: Independent retailers and luxury jewelers are locking in colored gemstone inventories early to counter supply crunches ahead of December delivery deadlines.
- Expansion of Digital B2B Trading Platforms: While physical viewing at premier bourses remains essential for high-ticket appraisal, hybrid digital platforms with standardized 360-degree microscopic video grading are shortening cross-border trade closing times.
- Heritage Meets Modern Geometry: High-jewelry designers are expected to blend ancient lapidary traditions—such as Mughal carved emeralds and classical Asian jade openwork—with sharp, minimalist, architectural settings throughout the upcoming season.